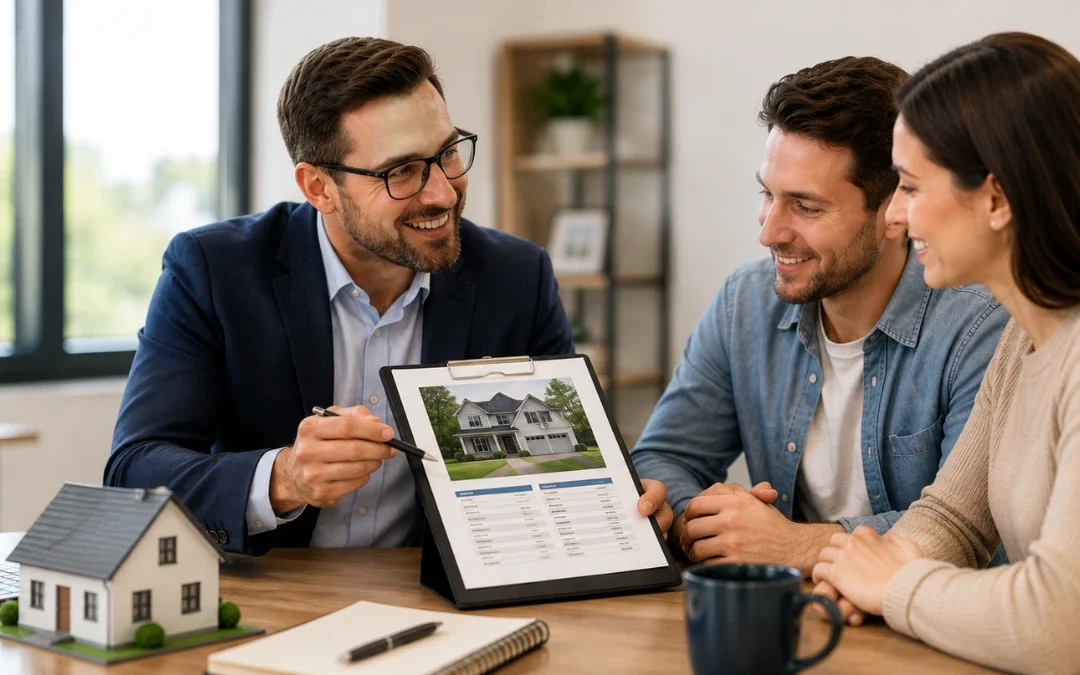
What does a mortgage broker do? Simply put, a mortgage broker is your personal shopper for a home loan. Instead of walking into a single bank and hoping for a fair deal, a broker looks at dozens of different lenders to find the exact perfect match for your wallet.
This saves you a massive amount of time and stress! One of the best mortgage broker benefits is that they handle all the heavy lifting and tricky paperwork for you. They hunt down the lowest interest rates to keep your monthly payments as small as possible, leaving more cash in your pocket.
What Does a Mortgage Broker Do?
Have you ever wondered exactly what does a mortgage broker do? Think of us as your personal guide through the wild maze of buying a home. We do the heavy lifting so you can focus on packing your boxes and picking out paint colors.
Definition and Role of a Mortgage Broker
A mortgage broker is a professional matchmaker. Instead of matching people for dates, we match home buyers with the perfect home loan. If you go straight to a bank, they only show you their own loans. But a broker works for you, not the bank. We look at hundreds of different loans from many different places to find the one that fits your exact budget. We sit right in the middle, acting as a helpful bridge that connects you to the lender who will give you the absolute best deal.
Key Responsibilities of a Mortgage Broker
You might be curious about our everyday mortgage broker duties. Our main goal is to make your life as easy as possible. Here is a quick look at our daily mortgage broker responsibilities:
- Learning your story: We sit down and look at your budget to figure out exactly what you can comfortably afford.
- Shopping around: We compare loans from dozens of lenders to hunt down the lowest interest rates for you.
- Gathering the paperwork: We help you collect your pay stubs, bank statements, and tax forms so everything is organized and ready to go.
- Sending the application: We fill out the tricky forms and send them off to the lender for you.
- Guiding you to the finish line: We answer your questions and hold your hand right up until you get the keys to your new home.
We handle the boring math and the huge stacks of paper. You get to plan where your furniture goes!
Why Choose a Mortgage Broker Over a Bank?
Walking into your local bank for a home loan is like going to a restaurant that only serves one dish. If you do not like it, you are out of luck. A broker gives you the entire menu.
Advantages of Working with a Broker
When you team up with us, you unlock some serious mortgage broker benefits. We do not work for a single bank; we work directly for you. We shop around with dozens of different lenders to find the exact right fit for your wallet.
If you are a first-time buyer, this means zero stress. We handle the messy paperwork and negotiate the details. Plus, it is no secret how mortgage brokers help clients save money on loans; we compare rates side-by-side to make sure you get the lowest interest possible. Lower interest just means more cash stays in your pocket every month.
How Brokers Provide Tailored Solutions
Not everyone fits perfectly into a standard bank’s neat little box. Maybe you run your own business, or maybe you are a high-net-worth buyer with money tied up in investments. Regular banks often look at these unique situations and just say no.
At Exclusive Mortgage Options, we do things differently. We can find flexible loans that fit your actual life. Whether you are self-employed or looking to protect your current assets, we find the path to “yes.” You get a customized plan built just for you, making your dream home a reality without the usual roadblocks.
How Much Do Mortgage Brokers Make?
Have you ever wondered what the person helping you buy a house takes home at the end of the day? Let’s talk about money and see exactly how they get paid for doing the heavy lifting.
Average Salary in the United States
The average mortgage broker salary in the US is pretty impressive, landing right around $170,700 a year. But most brokers do not get a standard weekly paycheck like a teacher or a nurse. Instead, they make money through a mortgage broker commission.
Here is how it works in simple terms: for every loan they help close, they usually earn 1% to 2% of the total loan amount. So, if they help a family secure a $300,000 home loan, the broker makes $3,000 to $6,000. Not too shabby, right? The best part is this fee is often paid by the lender, so it does not always come directly out of your pocket.
Factors Influencing Earnings
Of course, not every broker makes the exact same amount. A few big things change how much cash they bring in:
- Experience: A brand-new broker will usually make less than a seasoned pro who has been matching people with loans for twenty years.
- Location: Brokers working in cities with super expensive houses get larger loans approved, which means bigger commissions.
- Loan Volume: This just means how many loans they close. A broker who helps ten families buy homes in a month will earn a lot more than someone who only helps two.
The harder they work to find you a great deal, the better they do!
What Are the Benefits of Using a Mortgage Broker?
Buying a house feels a bit like running a marathon while juggling. You already have enough on your mind, so why add stressing over loan details to the list? Let’s look at the top mortgage broker benefits you get when you let a pro take the wheel.
Saving Time and Money
Imagine spending your weekends calling banks, waiting on hold, and filling out endless online forms. Sounds terrible, right? A mortgage broker takes that completely off your plate. They handle the frustrating phone calls and intense math for you. Plus, if you are wondering exactly how mortgage brokers help clients save money on loans, it all comes down to their negotiation skills. They know how to spot hidden fees and can often get sneaky bank charges reduced or waived entirely, keeping more cash in your pocket.
Access to Multiple Lenders and Better Rates
If you walk into a standard bank, they only show you their own loans. It is like going to a shoe store that only sells boots. But a mortgage broker has access to dozens, sometimes hundreds, of different lenders. They compare all the interest rates side-by-side to find the absolute best deal that fits your specific budget.
Simplifying the Loan Process
Getting a home loan approved requires a massive mountain of paperwork. Pay stubs, tax returns, bank statements, it gets messy fast. A broker steps in and organizes the chaos. Here is what they handle:
- Collecting and double-checking your documents.
- Filling out the tricky application forms correctly the first time.
- Translating confusing bank terms into plain, everyday English.
They simplify the entire journey, guiding you smoothly from the very first application right up to the moment you unlock your new front door.
How to Choose the Best Mortgage Broker?
Picking the right person to handle your home loan is a bit like choosing a good mechanic. You need someone honest, skilled, and ready to explain things without throwing confusing jargon at you. If you are wondering how to choose the best mortgage broker, it really comes down to knowing what to ask and what warning signs to spot.
Questions to Ask Before Hiring
Before you shake hands and hand over your financial paperwork, sit down and interview them. Here are three great questions to ask:
- How many lenders do you work with? A good broker should have a massive list of options, not just two or three buddies they always use.
- Can I get your mortgage broker fees explained? You deserve to know exactly how they get paid. Are you paying them out of pocket, or is the lender covering their check?
- Why should I pick a mortgage broker vs a loan officer? A smart broker will happily explain the difference. They should point out how they can shop around for you, while a bank’s loan officer is stuck selling you just one brand of loan.
Red Flags to Watch Out For
Even with great questions, you need to trust your gut. Watch out for these big warning signs:
- They dodge money questions: If they get weird or secretive about how they earn their commission, walk away.
- They promise the moon: Run far away from anyone who guarantees you a specific, super-low interest rate before they even glance at your credit score.
- They push you to borrow too much: A trusted pro respects your budget. If they keep trying to talk you into a massive loan that makes you nervous, find someone else.
Mortgage Broker vs. Loan Officer: What’s the Difference?
People often mix up these two jobs. While they both help you get money to buy a house, they play very different games.
Roles and Responsibilities Compared
Think of it this way: a bank loan officer works for just one bank. They can only offer you the specific loans that their bank sells. If you want to compare a mortgage broker vs a bank loan officer, the broker is like your own personal shopper. A broker does not work for one bank; they look at dozens of different lenders to find the exact perfect fit for your wallet.
Because they hustle to match buyers with so many different lenders, people often wonder, Do mortgage brokers earn more than loan officers? Usually, yes! Brokers can make more because they hunt down and close deals from a wide variety of sources, rather than just waiting for customers to walk into a single bank building.
Which One Should You Work With?
So, when looking at a mortgage broker vs loan officer, who gets your business? Here is a quick cheat sheet to help you decide:
- Choose a loan officer if you already have a deep, trusting relationship with your current local bank and they happen to offer a great deal.
- Choose a mortgage broker if you want someone to do the heavy lifting, shop around for the absolute lowest interest rates, or if you have a unique financial situation like running your own business.
A broker simply gives you way more choices and does the hard math for you!
Can a real estate agent also be a mortgage broker?
Have you ever wished the person helping you find a house could also just handle the home loan for it? Well, sometimes they can! Let’s talk about whether your real estate agent can safely wear two hats at the same time.
Dual Roles and Their Benefits
Yes, a real estate agent can absolutely also be a mortgage broker! When one person does both jobs, it creates a super simple “one-stop shop” for you. You completely skip the headache of passing messages back and forth between your agent and your lender because they are the exact same person.
One of the biggest mortgage broker benefits in this setup is pure speed. Since they already know exactly which house you want to buy and how much you can comfortably spend, they can jump right into their normal mortgage broker duties without missing a beat. It saves you time and keeps all your paperwork in one tidy pile.
Legal and Ethical Considerations
But is this setup allowed everywhere? The short answer is mostly yes, but with very strict rules in place to keep you safe. The law requires these double-duty agents to be completely honest with you. They must clearly explain how they get paid for both jobs so you never face any secret hidden fees.
If an agent ever tries to force you to use their loan services just to buy a house, run the other way. A trustworthy pro will always remind you that you are totally free to shop around!
What to Expect at the Closing Table
You did it! You found the perfect house, and your mortgage broker handled all the messy paperwork. Now, it is time for the final and most exciting step: closing day.
Finalizing Your Home Loan
Closing day is simply the day you sign the official papers and finally pay for the house. If you are wondering what your broker does during this last step, they are still right by your side. A trusted broker reviews the final math to make sure there are no surprise fees hiding in the fine print. They double-check that your interest rate and monthly payments match exactly what you agreed on. You just show up, bring your favorite pen, and sign your name.
Getting the Keys to Your New Home
Once the ink dries, the lender sends the money to the seller. That is it; the house is officially yours! Working with a trusted expert means you get to skip the usual closing day panic. You walk in feeling confident, knowing you got the absolute best deal possible.
Buying a home should be fun, not frustrating. Having a professional in your corner turns a scary process into a smooth ride. Ready to make your big move? Reach out to our team at Exclusive Mortgage Options. We will help you secure your dream home without the headache. Let’s get started on your journey today!
Steps to Becoming a Mortgage Broker in the US
So, you want to help people buy their dream homes and earn a great mortgage broker salary while doing it? Stepping into this career is a fantastic move with plenty of mortgage broker benefits, like having flexible hours and being your own boss. Here is exactly how you get started.
Education and Licensing Requirements
You do not need a fancy four-year college degree to jump into this job. First, you have to take a 20-hour pre-licensure class. Think of this as a quick crash course in your future everyday mortgage broker duties.
After you finish the class, you must pass a big national exam called the SAFE MLO test, which is run by the NMLS. Passing this test proves you know the rules of the game. Next, you will need to pass a standard criminal background check and a credit check. This just shows the state that you are highly trustworthy with other people’s money. Once you check all those boxes, you get your official license!
Continuing Education and Professional Development
The learning does not stop once you get your license. Laws about money and housing change all the time. To keep your license active, you have to take about eight hours of continuing education classes every single year. It keeps your skills sharp and ensures you are always giving families the safest, smartest advice when they are ready to buy a house.
Exclusive Mortgage Options: How We Simplify Home Financing
Buying a house is a massive milestone, but the paperwork can feel like a heavy anchor. At Exclusive Mortgage Options, we take that weight off your shoulders. Our goal is to make getting a home loan as easy as ordering your favorite pizza.
Personalized Loan Solutions for Every Client
Your life is totally unique, which means your home loan should be, too. We do not believe in a one-size-fits-all approach. Whether you are buying your very first house, running your own small business, or trying to lower your current monthly payments, we build a plan just for you. We dive deep into your budget and shop around with our huge network of lenders. This way, we find the exact loan that fits your wallet perfectly, keeping more cash in your pocket every month.
Why Clients Trust Exclusive Mortgage Options
Trust is earned, not given. People love working with us because we treat you like family, not just another file on a desk. We promise zero hidden fees, no confusing bank jargon, and total honesty from day one. If a deal does not make sense for your budget, we will tell you straight up. We hold your hand through the entire process, answering your questions until you finally turn the key in your new front door. We do the heavy lifting so you can focus on the fun part: making your new house a home.
FAQs
How Do Mortgage Brokers Get Paid?
Usually, the lender pays them a commission. Think of this as a small slice of the pie, about 1% to 2% of your total loan amount, given to them after you actually buy your house. Sometimes, you might pay a flat fee yourself, but a trusted broker will always explain their pay structure clearly before you sign anything. No hidden surprises!
Are mortgage brokers regulated?
Yes, strictly! You can rest easy knowing they are not just making up rules as they go. Every broker must pass tough national exams, clear deep background checks, and hold an official state license. Government groups watch them closely to make sure they follow the law and treat your money safely.
What Documents Do I Need to Work with a Broker?
To get started, your broker simply needs proof of who you are and how much money you make. Plan to gather a few basic items:
- Your most recent pay stubs.
- Tax returns from the last two years.
- A couple of months of bank statements.
- A standard photo ID, like your driver’s license.
Having these basic papers ready to go makes the whole journey incredibly fast and smooth.
Conclusion
Buying a house is a massive adventure, but you do not have to hike the trail alone. Teaming up with a mortgage broker is like hiring a genius trail guide who knows exactly where all the hidden traps are. They do the heavy lifting, compare the messy numbers, and fight to keep more of your hard-earned cash in your wallet.