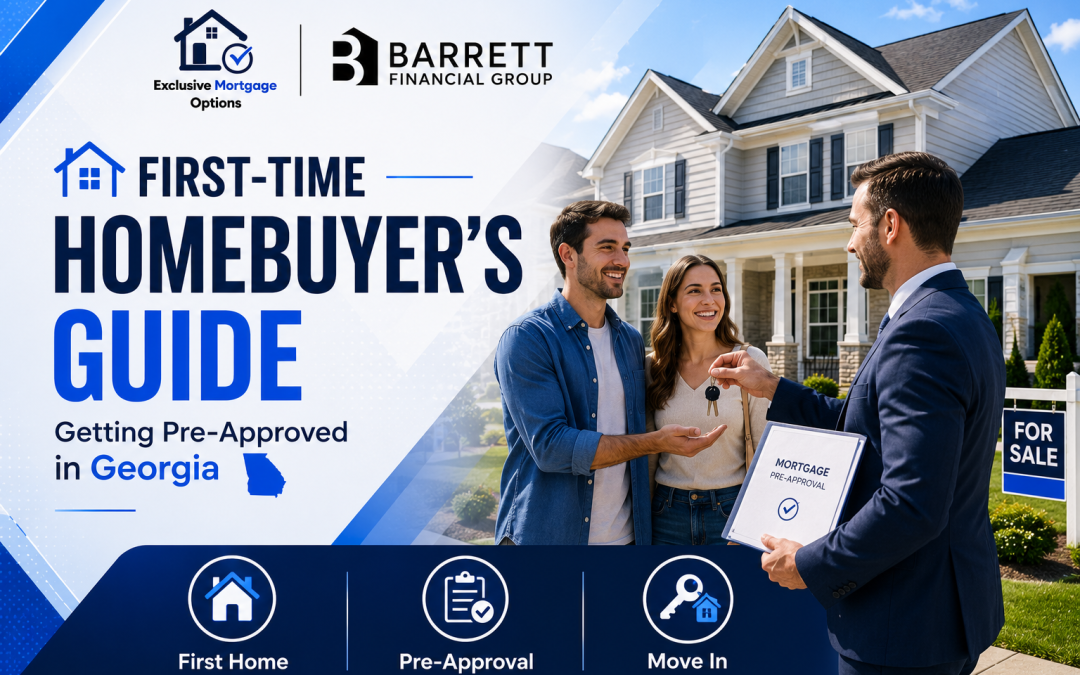
Quick answer: To get pre-approved for a mortgage in Georgia, you’ll need a credit score of at least 580–620 for most loan programs, proof of income (pay stubs, W-2s, tax returns), bank statements, and a soft or hard credit pull from a licensed lender. Most Georgia buyers receive a pre-approval letter within 24–72 hours of submitting documents. Pre-approval is different from pre-qualification — pre-approval involves verified documentation and carries real weight with sellers, while pre-qualification is just an estimate.
If you’re planning to buy your first home in Roswell, Alpharetta, Sandy Springs, Dunwoody, or anywhere else in metro Atlanta, here’s exactly what pre-approval involves, what it costs you, and how to get it right the first time. Ready to start? You can get pre-approved with Exclusive Mortgage Options directly, or keep reading for the full breakdown.
What Does “Mortgage Pre-Approval” Actually Mean?
Pre-approval is a lender’s conditional commitment to fund a home loan up to a certain amount, based on your verified income, assets, debts, and credit. It’s not a guarantee of final approval (that comes later, after underwriting and appraisal), but it tells you, and any seller you make an offer to, that you’re a serious, qualified buyer.
Pre-approval is different from pre-qualification in one key way: pre-qualification is based on numbers you report yourself, with no documentation review. Pre-approval means a lender has actually pulled your credit and reviewed real paperwork. In a competitive market like Roswell real estate or Alpharetta real estate, sellers and listing agents will often only take offers seriously when they come with a pre-approval letter, not just a pre-qualification.
Why Getting Pre-Approved Should Be Your First Step
Before you tour a single home, pre-approval tells you three things:
- Your real budget — not a guess, but a number based on your actual income, debt, and credit
- Your loan options — FHA, conventional, VA, or USDA, each with different down payment and credit requirements
- Your negotiating power — a pre-approval letter shows sellers you can close, which matters in multiple-offer situations across Fulton and DeKalb counties
Skipping this step is one of the most common (and costly) mistakes first-time buyers make. Falling in love with a home before knowing what you actually qualify for often leads to disappointment or a rushed, weaker offer later. If you’re weighing whether now is even the right time to buy, our breakdown on buying a home in Dunwoody covers current local market conditions in more depth.
Documents You’ll Need for Pre-Approval
Most lenders ask for the same core paperwork:
- Two years of W-2s or tax returns (more documentation if you’re self-employed)
- Recent pay stubs (last 30 days)
- Two to three months of bank statements
- Government-issued ID
- Proof of any additional income (bonuses, alimony, rental income)
- Documentation for large deposits or gift funds, if applicable
Having these ready before you contact a lender is the single biggest thing you can do to speed up the process.
Credit Score and Down Payment Basics
Credit requirements vary by loan type:
- FHA loans generally allow credit scores as low as 500–580, with a minimum 3.5% down payment at 580+
- Conventional loans typically require 620 or higher
- VA loans (for eligible veterans and service members) often have no set minimum from the VA itself, though lenders commonly look for 580–620
- USDA loans for eligible rural and suburban Georgia properties usually want 640+
For a deeper side-by-side breakdown of which program fits your situation, see our guide on FHA vs. conventional loans. Your down payment doesn’t have to come entirely out of pocket, either — Georgia offers real help here through the state’s official down payment assistance program.
Georgia Down Payment Assistance for First-Time Buyers
The Georgia Dream Homeownership Program, run by the Georgia Department of Community Affairs, offers first-time buyers up to $10,000 in down payment and closing cost assistance (or up to $12,500 for eligible public service workers, including teachers, nurses, and law enforcement, and for households with a disabled family member). It’s structured as a zero-interest, deferred second loan that requires no monthly payment as long as you stay in the home. Most participating lenders look for a minimum 640 credit score, along with completion of a required homebuyer education course.
Because eligibility, income limits, and loan limits are set and updated by government agencies, it’s worth confirming current figures directly through the Georgia DCA’s Georgia Dream program page before budgeting around a specific number, since limits vary by county and household size. We also break down down payment assistance options for Georgia buyers in more detail, including how to layer Georgia Dream on top of an FHA or conventional loan.
How Long Does Pre-Approval Take?
For most W-2 employees with straightforward finances, pre-approval takes anywhere from same-day to about 3 business days once all documents are submitted. Self-employed borrowers or those with more complex income may take a bit longer, since additional documentation (like profit-and-loss statements) is often required. A pre-approval letter is typically valid for 60–90 days, after which your lender may need to refresh your credit and income documentation. Once you’re ready to move, our step-by-step mortgage process timeline walks through what happens between pre-approval and closing day.
Does Getting Pre-Approved Hurt Your Credit?
A pre-approval involves a hard credit inquiry, which can cause a small, temporary dip in your credit score — usually just a few points. Multiple mortgage inquiries within a short shopping window (typically 14–45 days, depending on the scoring model) are generally counted as a single inquiry for scoring purposes, since credit bureaus expect rate shopping. This means comparing a few lenders won’t meaningfully hurt your score. For more detail on how mortgage shopping affects your credit, the Consumer Financial Protection Bureau’s guide to shopping for a mortgage is a solid, unbiased resource. If your score needs some work first, our post on improving your credit score before applying is a good starting point.
Loan Limits: What You Can Actually Borrow
FHA and conventional loan limits are set annually by county and change every year, so rather than quote a number that may already be outdated, always check the current figure through HUD’s official FHA loan limit lookup tool before assuming what you qualify for. If you’re looking at a higher-priced home in Sandy Springs or North Fulton that may exceed standard limits, our jumbo loan guide for metro Atlanta buyers covers what to expect.
Working With a Local Mortgage Broker vs. a Big Bank
A local, licensed mortgage broker in Roswell works with multiple lenders at once, which often means more loan options and more flexibility on rate and terms than walking into a single bank branch. For first-time buyers, that flexibility matters — especially when you’re trying to combine a first mortgage with a down payment assistance program like Georgia Dream, which not every lender is approved to offer. The same applies whether you’re buying in Roswell or working with a mortgage broker in Alpharetta — a broker familiar with local property values, HOA norms, and county-specific loan limits can help you avoid surprises later in underwriting. See our full breakdown of why a mortgage broker can save you money versus a bank for a closer look at the difference.
Frequently Asked Questions
What credit score do I need to get pre-approved for a mortgage in Georgia? It depends on the loan type — FHA loans can allow scores as low as 500–580, conventional loans typically want 620+, and Georgia Dream down payment assistance generally requires 640+.
What’s the difference between pre-qualification and pre-approval? Pre-qualification is based on self-reported numbers with no document review. Pre-approval involves a credit pull and verified documentation, and carries far more weight with sellers.
How long does mortgage pre-approval take in Georgia? Typically 24–72 hours once all documents are submitted, though it can take longer for self-employed borrowers or more complex financial situations.
Does pre-approval hurt my credit score? It causes a small, temporary dip from the hard inquiry, but multiple mortgage inquiries within a short shopping window are generally treated as one inquiry by scoring models.
Can first-time buyers in Georgia get help with their down payment? Yes. The Georgia Dream Homeownership Program offers up to $10,000–$12,500 in down payment and closing cost assistance for eligible first-time buyers.
How long is a pre-approval letter valid? Most pre-approval letters are valid for 60–90 days before needing updated documentation.
Ready to Get Pre-Approved?
If you’re planning to buy your first home in Roswell, Alpharetta, or anywhere else in metro Atlanta, getting pre-approved is the step that turns “someday” into an actual move-in date. Exclusive Mortgage Options can walk you through your loan options, including Georgia Dream down payment assistance, and get you a pre-approval letter you can hand to a seller with confidence.
Sherry von Klitzing, NMLS #1004049, is a mortgage broker operating under Barrett Financial Group, NMLS #181106, licensed in Georgia, Alabama, Florida, North Carolina, and California. This article is for informational purposes only and does not constitute a loan commitment or guarantee of specific loan terms.